Many homeowners in the UAE continue paying the same mortgage for years without checking whether their current terms are still competitive.
But a mortgage should not simply be left unchanged for its entire term.
Interest rates move, EIBOR changes, fixed-rate periods expire, and banks introduce different mortgage offers over time. Your own financial situation may also improve.
As a result, a mortgage that was competitive when you originally took it may no longer be the best option several years later.
The key is knowing when refinancing makes financial sense — and when it does not.
What Does Mortgage Refinancing Mean?
Mortgage refinancing means changing the structure of your existing mortgage to obtain more suitable terms.
This can happen in different ways.
You may be able to review or reprice your mortgage with your existing bank, or you may transfer the outstanding mortgage to another bank through a mortgage buyout or refinancing arrangement.
The objective is not simply to find a lower advertised rate.
The real objective is to determine whether the new mortgage provides a meaningful financial benefit after all costs are considered.
Why Timing Matters
Timing is one of the most important factors in refinancing.
If you refinance too early, the cost of changing the mortgage may be greater than the savings.
If you wait too long, you may continue paying a higher rate for months or even years unnecessarily.
A refinancing decision should therefore compare:
Potential Future Savings
against
Cost of Changing the Mortgage
The difference between the two determines whether refinancing is financially worthwhile.
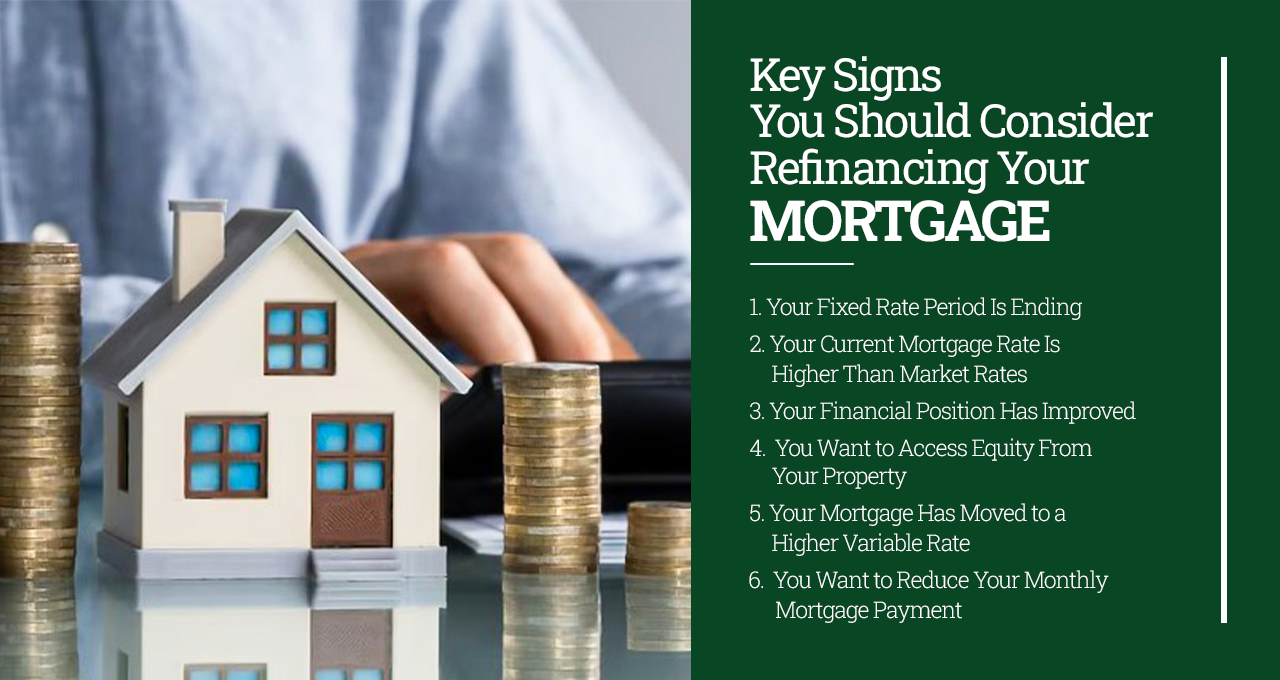
Key Signs You Should Review Your Mortgage
1. Your Fixed-Rate Period Is Ending
The end of your fixed-rate period is one of the most important times to review your mortgage.
Many UAE mortgages move after the fixed period to a variable structure such as:
3-Month EIBOR + Bank Margin
or another EIBOR-linked structure stated in the mortgage agreement.
If the resulting variable rate is significantly higher than your existing fixed rate, your monthly mortgage payment may increase.
Reviewing your mortgage before the fixed period ends gives you time to compare your existing bank’s terms with other available options.
2. Your Current Mortgage Rate Is Higher Than Available Market Rates
If your current mortgage rate is materially higher than rates available for a similar borrower profile, it may be worth reviewing your options.
Even a relatively small rate difference can become meaningful when the outstanding mortgage balance is large.
Simple Illustration
Assume you have an outstanding mortgage balance of AED 2,000,000.
As a simple annualized illustration:
- A 0.25% rate difference represents approximately AED 5,000 per year
- A 0.50% rate difference represents approximately AED 10,000 per year
- A 1.00% rate difference represents approximately AED 20,000 per year
These figures are not exact mortgage-payment savings.
Actual savings depend on the outstanding balance, remaining tenure, repayment structure, new mortgage rate and the costs involved in refinancing.
The purpose of the example is to show that even a small rate difference can become significant on a large mortgage balance.
3. Your Mortgage Has Moved to a Higher Variable Rate
EIBOR is an important benchmark used for many UAE variable-rate mortgages. The Central Bank of the UAE identifies EIBOR as a reference rate used for financial transactions including mortgages.
If your fixed-rate period has ended and your mortgage is now priced at:
EIBOR + Bank Margin
your applicable rate may move as EIBOR changes.
This can be a good time to compare your existing mortgage with current market options.
However, EIBOR alone should not determine whether you refinance.
Your bank margin, minimum floor rate, remaining tenure and switching costs also need to be considered.
4. Your Financial Position Has Improved
Your eligibility today may be stronger than when you originally took the mortgage.
For example:
- Your salary may have increased
- Your business income may have improved
- Existing personal loans may have been repaid
- Credit card liabilities may have reduced
- Your overall credit profile may have improved
A stronger financial profile may allow you to access mortgage options that were not available when your original mortgage was approved.
This does not guarantee better terms, but it is a reasonable reason to review the market.
5. You Want to Reduce Your Monthly Mortgage Payment
Some homeowners refinance because their priority is improving monthly cash flow.
Depending on the available terms, refinancing may help reduce the monthly instalment through:
- A lower mortgage rate
- A different mortgage structure
- A change in remaining tenure
However, a lower monthly instalment does not automatically mean you are saving money.
For example, extending the loan over a longer period can reduce the monthly payment but increase the total amount paid over the remaining mortgage term.
Both monthly affordability and total cost should therefore be considered.
6. You Want to Access Equity From Your Property
If your property’s value has increased and your outstanding mortgage has reduced, you may have built equity in the property.
Depending on your eligibility and the bank’s lending criteria, refinancing may sometimes be combined with an equity-release structure.
The amount available will depend on factors such as:
- Current property valuation
- Outstanding mortgage balance
- Applicable loan-to-value limits
- Income and affordability
- Existing liabilities
- Individual bank policy
Equity release should be assessed separately from simple rate refinancing because the objective is different: you are increasing access to cash rather than only reducing the cost of the existing mortgage.
When Refinancing May Not Make Sense
Refinancing is not automatically the right decision.
You may be better staying with your existing mortgage if:
- Your current rate is already competitive
- Your outstanding mortgage balance is relatively low
- You plan to sell the property soon
- The expected savings are small
- Switching costs are higher than the potential benefit
- You are already close to the end of your mortgage term
This is why refinancing should be based on numbers rather than simply reacting to a lower advertised rate.
The Most Important Calculation: Break-Even Point
The break-even point is one of the most useful ways to decide whether refinancing makes sense.
It tells you how long it will take for your savings to recover the cost of switching.
For example:
Assume refinancing costs you AED 12,000.
If the new mortgage saves you approximately AED 1,000 per month:
AED 12,000 ÷ AED 1,000 = 12 months
Your break-even period would be approximately one year.
If you expect to keep the mortgage for several years after that point, refinancing may make financial sense.
But if you plan to sell the property within six months, refinancing may not be worthwhile even if the new rate looks attractive.
What Costs Should You Consider?
Before refinancing, calculate all applicable costs.
These may include:
- Early settlement fee
- New bank processing fee
- Property valuation fee
- Mortgage registration costs
- Liability letter or documentation charges
- Other applicable transaction costs
For UAE home loans and financing, the Central Bank of the UAE caps early settlement fees at a maximum of 1% of the outstanding balance or AED 10,000, whichever is lower.
The exact total cost will depend on the banks and transaction.
This is why comparing interest rates alone can give an incomplete picture.
Reprice With Your Current Bank or Move to Another Bank?
Before transferring your mortgage, it may be worth reviewing what your existing bank can offer.
Repricing or Restructuring With Your Existing Bank
Your current bank may offer a revised rate or mortgage structure depending on its policy.
The advantage is that the process may be simpler and may involve fewer switching costs.
Mortgage Buyout or Refinancing to Another Bank
Another bank may offer a more competitive mortgage structure and settle the outstanding financing with your existing bank.
The CBUAE framework allows borrowers to transfer financing between banks, subject to the applicable conditions and charges.
Whether staying or moving is better depends on the total financial outcome, not simply the advertised rate.
How Often Should You Review Your Mortgage?
You do not need to change your mortgage every year.
But reviewing it periodically is sensible.
Important times to review include:
- Before your fixed-rate period ends
- After a significant change in mortgage rates
- When your variable rate becomes expensive
- When your financial situation improves
- When your property value changes significantly
An annual mortgage review can also help you understand whether your existing arrangement remains competitive without necessarily refinancing.
Common Refinancing Mistakes
Homeowners should avoid:
- Looking only at the headline interest rate
- Ignoring early settlement and switching costs
- Extending the mortgage term without considering total interest
- Waiting until after the fixed rate has already expired
- Comparing one bank instead of several suitable options
- Refinancing without calculating the break-even period
- Assuming a lower monthly payment always means a cheaper mortgage
The correct refinancing decision should consider the entire remaining mortgage, not just the first year.
How Prime Rate Hub Helps You Decide
At Prime Rate Hub, the objective is not to recommend refinancing simply because another bank advertises a lower rate.
We can help homeowners:
- Review their current mortgage
- Compare options across 20+ UAE banks
- Assess the existing rate, bank margin and mortgage structure
- Calculate potential savings
- Estimate the break-even period
- Compare switching costs
- Review repricing with the existing bank versus a mortgage buyout
- Manage the refinancing or buyout process when changing the mortgage makes financial sense
Sometimes the best recommendation will be to refinance.
Sometimes it will be to stay with the existing bank.
The important point is to make the decision based on the numbers.
Frequently Asked Questions
When is the best time to refinance a mortgage in the UAE?
One of the most important times is before your fixed-rate period ends. It may also be worth reviewing your mortgage when your current rate becomes significantly higher than available market rates.
How do I know if I am overpaying on my mortgage?
Compare your current rate, bank margin and mortgage structure with suitable current market options. The comparison should also include the costs of switching and your remaining mortgage term.
How much can refinancing save?
Savings depend on your outstanding mortgage balance, current rate, new rate, remaining tenure and refinancing costs.
For example, a 0.50% rate difference on an outstanding balance of AED 2 million represents approximately AED 10,000 per year on a simple annualized basis, although actual mortgage savings will differ.
What is the break-even point in mortgage refinancing?
It is the time required for your refinancing savings to recover the cost of changing the mortgage.
If switching costs AED 12,000 and you save AED 1,000 per month, the break-even period would be approximately 12 months.
Can I refinance my mortgage at any time?
A mortgage can potentially be reviewed at different stages of its term, subject to bank eligibility, applicable mortgage terms and switching costs. The financial benefit should be assessed before proceeding.
Is refinancing the same as a mortgage buyout?
The terms are sometimes used together in the market. A mortgage buyout generally refers to transferring your outstanding mortgage from one bank to another.
Reviewing or repricing with your existing bank is different because the mortgage remains with the same lender.
How long does mortgage refinancing take in the UAE?
A straightforward refinancing or mortgage buyout can often take several weeks, but the timeline depends on the existing bank, new bank, property valuation, documentation and registration process.
Does EIBOR affect refinancing decisions?
Yes, particularly when your existing mortgage is on a variable EIBOR-linked structure. However, EIBOR should be considered together with the bank margin, floor rate, remaining tenure and refinancing costs.
Conclusion
Mortgage refinancing in the UAE should not be treated as an automatic response to every change in interest rates.
The right time to refinance depends on your existing mortgage, current market conditions, remaining balance, financial profile and the cost of switching.
The most important question is not:
“Can I get a lower rate?”
It is:
“Will refinancing provide a meaningful financial benefit after all costs are considered?”
Reviewing your mortgage at the right time, calculating the break-even point and comparing the full mortgage structure can help you make a more informed long-term decision.