UAE nationals
Mortgage Eligibility in UAE
Eligibility for Mortgages in UAE
Mortgage eligibility in the UAE determines the possibility of obtaining financing for purchasing or refinancing property. The banks will evaluate the applicant considering the income, liability, employment, and property aspects. It is important for the buyer to know about the eligibility criteria so that he or she will be prepared to obtain the mortgage without any delay. To see how eligibility works for specific communities, read our guides for Al Reef, Al Ghadeer and Masdar City.
Who Can Apply for a Mortgage in UAE
Mortgage financing is available for:
Each category has different eligibility requirements and financing limits.
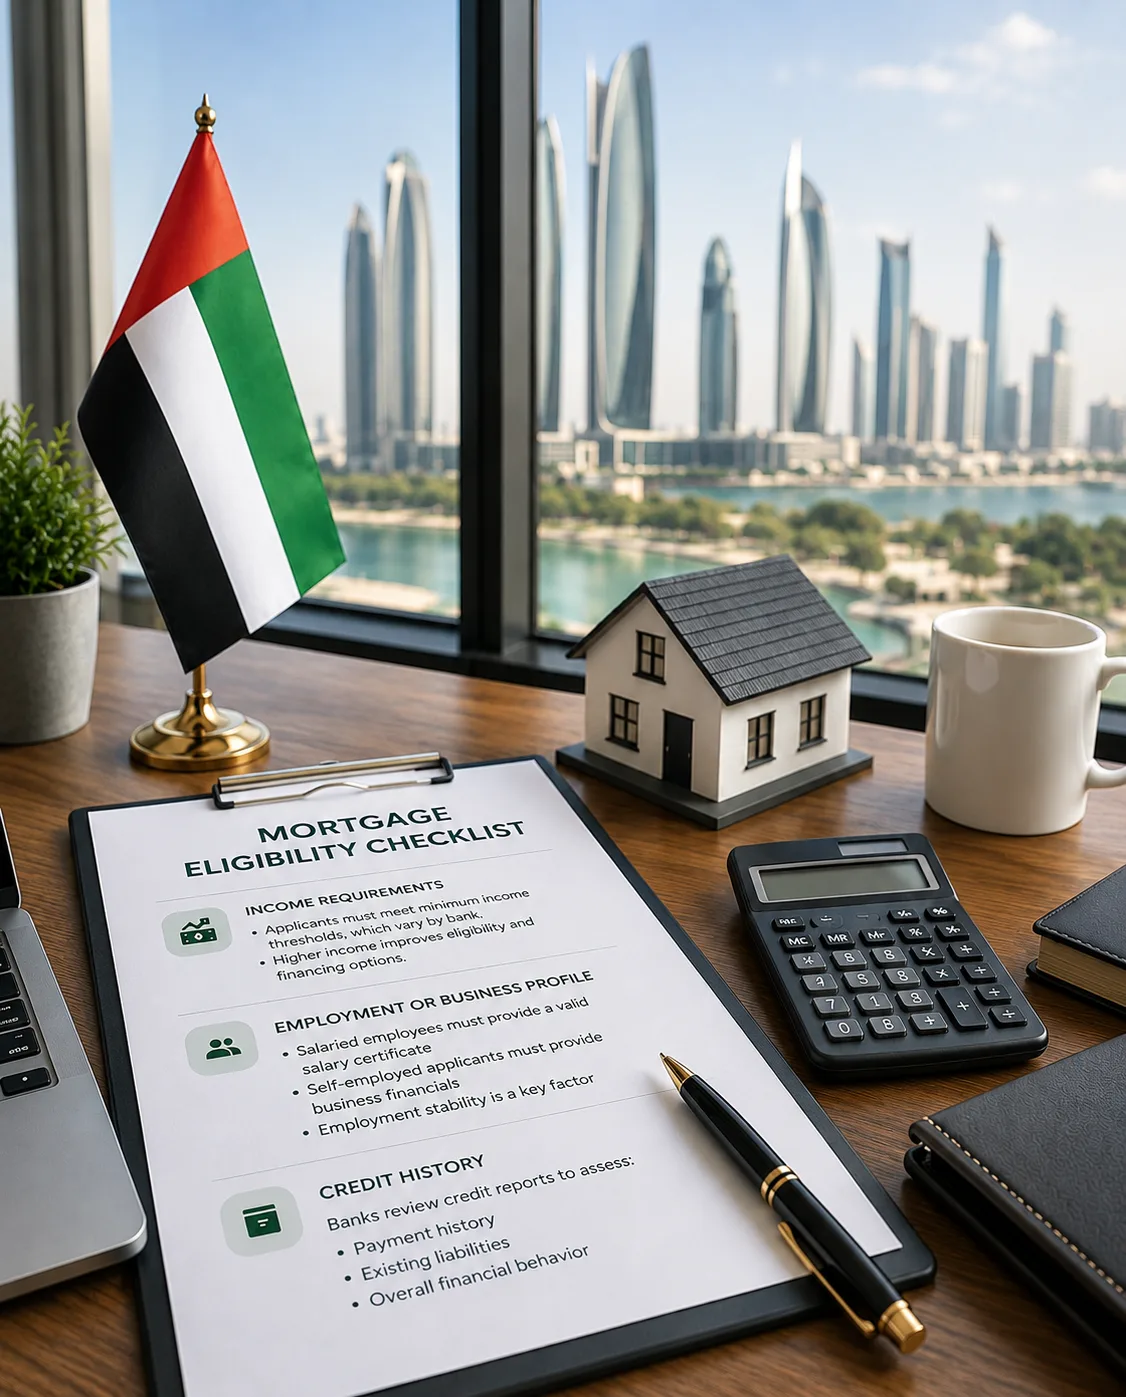
Important Eligibility Criteria
In order to get a mortgage in the UAE, banks consider many criteria of the applicant, including:
Criteria That Affect Mortgage Eligibility
The mortgage rate offered by the banks depends on various criteria including:
Two borrowers applying to the same bank may receive different offers.
Maximum Mortgage Amount
Pre-Approval Process
Common Reasons for Rejection
Free Mortgage Eligibility Check
Planning to buy property in the UAE?
Prime Rate Hub offers a structured eligibility assessment based on your profile and selected building.
We work with the top banks in UAE
FAQ
Mortgage Eligibility
What is the minimum salary requirement for a mortgage in the UAE?
The minimum salary requirement depends on the bank; most banks ask for a salary that can meet DBR restrictions and mortgage payments.
Can I get a mortgage if I have current debts?
Yes, provided that the overall monthly payment is not more than 50% of your income according to the DBR regulations.
How do banks calculate mortgage eligibility?
Banks consider such factors as income, liabilities, DBR, property value, and bank requirements when calculating mortgage eligibility.
Are self-employed people eligible for a mortgage?
Yes, they are, but there are certain conditions.
Are non-residents eligible for a mortgage in the UAE?
Yes, but mortgage eligibility is stricter and requires better financial backgrounds.
Does my credit score affect mortgage approval?
Yes, credit score influences mortgage approval.
What is a mortgage pre-approval?
Mortgage pre-approval is a preliminary statement from a bank about the possible amount of a mortgage before selecting a property.